

Chime® – Fee-Free Banking
by Chime
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 10.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
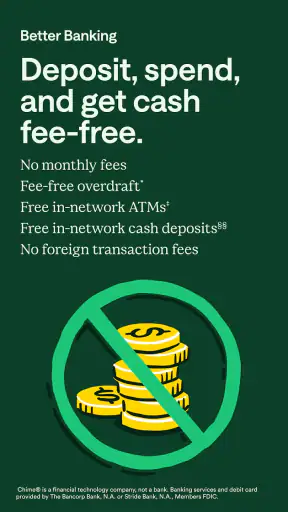
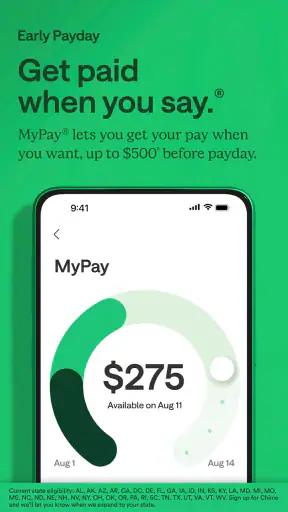
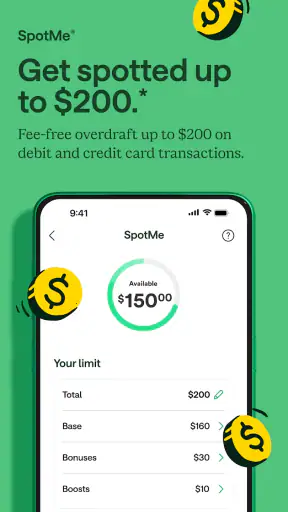
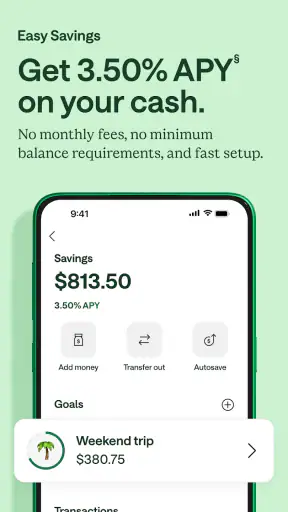
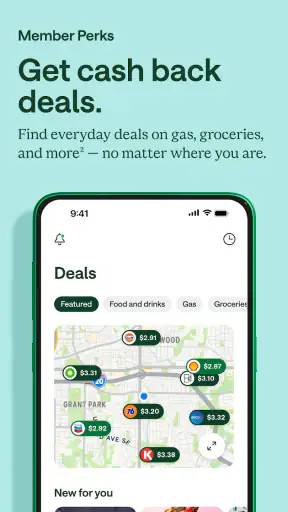
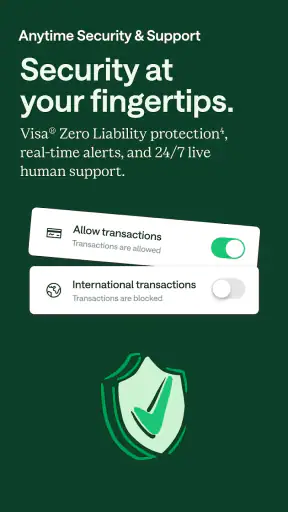
 Analysis by Getfullapps
Choosing a banking app is different from choosing a game or a simple budgeting tool. You are trusting it with money, identity checks, recurring payments, and the everyday details that can make a payday feel either smooth or stressful. I spent time with Chime® – Fee-Free Banking to see how approachable it feels for someone opening the app for the first time, not just for an experienced mobile-banking user. My overall impression is that it is designed to make routine banking feel less intimidating, especially if you want to manage your account from a phone rather than visit a branch.
Chime is a free finance app from Chime, and it is available for everyone rather than being aimed at a narrow age group. Its public reception is strong, with a 4.7 average from around 1.1 million ratings and more than 10 million installs. Those figures do not replace personal judgment, but they do suggest that the app has become a familiar choice for people who want a mobile-first way to handle everyday banking.
What to expect before you begin
The first thing I would tell a new user is to think of Chime as a central place for ordinary money tasks, not as a complete replacement for every financial product. It is most useful when you want to check your balance, follow incoming money, review spending, and keep an eye on activity without opening a desktop website. The app’s value comes from reducing small points of friction that add up during a normal week.
That focus makes it a good fit for someone who is starting to manage money independently, someone who prefers phone-based banking, or someone who wants a dedicated account for everyday spending. I can also see it working well for a person who wants to separate regular expenses from savings goals by using a clear routine around incoming money and scheduled bills.
It is less compelling for a user who needs advanced investing, detailed business accounting, complex international banking, or a broad collection of financial products in one place. A traditional bank may offer a wider branch network and more specialized services. Another finance app may be better for long-term planning or detailed spending analysis. Chime’s strength is not trying to be everything; it is keeping common banking actions close at hand.
The app has been available since March 28, 2014, and the current version is 5.332.0. It requires at least OS 10, so I would check the operating system on an older phone before planning a switch. That is a small step, but it prevents the frustrating situation of preparing to move your finances and discovering that the device cannot run the current app.
How I would prepare for the first session
Before installing it, I would have a stable internet connection, access to the email address and phone number I plan to use, and the personal details needed for an account application. I would also decide in advance why I am opening the account. “I want a place for everyday purchases” leads to a clearer setup than “I will see what it does.” A specific purpose makes later choices easier.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
For example, if your goal is to manage weekly spending, decide which income or transfer will support that routine and which bills should remain elsewhere at first. If your goal is to build a separate cushion, decide how much you can move regularly without putting rent, food, or transport at risk. The app cannot make those decisions for you, but it can become more useful when you give it a simple job.
I also recommend treating the first login as a security task rather than rushing through it. Use a password you do not reuse elsewhere, keep your phone’s lock screen protected, and read each confirmation screen before continuing. Banking apps deserve a slower setup than a social app because a mistaken tap can affect access to money or important notifications.
Getting through setup without unnecessary stress
Chime’s onboarding is built around creating access to a financial account, so new users should expect identity and account-related questions rather than a casual sign-up. The best approach is to enter information consistently and avoid guessing. If a form asks for a detail you are unsure about, pause and verify it instead of trying several variations. That can save time later if the app needs to match your information.
Once the account is ready, I would spend a few minutes learning the home screen before moving money or changing settings. Look for the balance area, recent activity, and the controls connected to transfers or account management. You do not need to understand every option on the first day. The goal is simply to know where the important information appears and how to return to it.
A useful beginner habit is to make a small mental map: where the current balance is shown, where recent transactions are listed, and where you would go if something looks unfamiliar. This is more valuable than tapping through every menu. When a payment is pending or a deposit has not appeared yet, knowing where to check prevents unnecessary panic.
Another practical tip is to keep your first setup conservative. Do not immediately reorganize every financial obligation around a new account. Use it for a controlled purpose until you are comfortable with the timing of your income, payments, and notifications. This gives you a chance to see how the app fits your real routine without making one unfamiliar process responsible for everything at once.
The first successful action matters more than exploring every feature
For a first-time user, I define success as completing one useful task and confirming where the result appears. That might mean checking the account balance after an incoming transaction, reviewing an item in recent activity, or arranging your spending routine so the app has a clear role. The exact action will depend on your situation, but the principle is the same: do one small thing, then verify it.
Imagine that you install Chime before a busy workweek because you want a simpler way to monitor everyday expenses. After setup, you open the account, review the available balance, and check the activity list after your first purchase. That simple loop—act, return to the app, confirm—builds confidence much faster than reading every screen without using the account.
I find this especially important with banking products because users often confuse an action being accepted with an action being completed. A transfer or payment may have a status that changes over time. Rather than assuming that a button press means the money has fully moved, return to the activity area and read the status. That habit is useful in Chime and in any financial app.
For someone paid on a regular schedule, a sensible first-week workflow is to check the account when money arrives, identify the amount available for ordinary spending, and review activity after a few purchases. This is not a complicated budget, but it gives you a realistic picture of how the app communicates money movement. It also helps reveal whether you prefer checking once a day, several times a week, or only around major transactions.
One non-obvious advantage of this approach is that it separates the app’s interface from your financial assumptions. If the balance looks different from what you expected, you can first inspect recent activity and timing before concluding that the app is wrong. In my experience, that distinction prevents many avoidable support requests and helps a new user become more self-sufficient.
Where new users can become confused
The most common source of confusion in mobile banking is the difference between available money, recent activity, and transactions that are still being processed. A number on the main screen is useful, but it is not a substitute for reading the transaction details. If you have just made a purchase, received money, or arranged a movement between accounts, give the activity view your attention as well.
I would also avoid treating every notification as a final financial statement. Notifications are helpful reminders, but the account screen is where I would verify the current status. If a message seems inconsistent with what you see, take a screenshot for your own records, review the transaction details, and use the app’s support path rather than repeatedly attempting the same action.
Another point that deserves care is the difference between a banking app and a budgeting coach. Chime can help you observe activity and create a routine, but it will not automatically understand your priorities. If you have irregular income, shared household expenses, or several accounts, you may still need a spreadsheet or a dedicated budgeting service. I would use Chime as the reliable place to monitor its own account, then use another tool if you need a complete view of your financial life.
Users should also be realistic about “fee-free” language. The app is free to download and use, but banking situations can involve conditions outside the simple act of installing an app. Before relying on any particular money movement or service, read the relevant in-app explanation and terms. I would never make a financial decision based only on a short store phrase, especially when timing or eligibility matters.
Privacy and security are another area where convenience should not replace attention. Keep the app updated, protect your device, and do not share verification messages with anyone who contacts you unexpectedly. If a request feels urgent or unusual, stop and verify it through the official in-app route. This is not a criticism unique to Chime; it is a basic rule for handling any account connected to money.
Small workflows that make the app more useful
One workflow I recommend is a “transaction check” after any unusual purchase. Open the activity list, confirm the merchant or description, note whether the item is pending or completed, and only then update your personal budget. This prevents a temporary authorization from being mistaken for a final charge and keeps your outside records more accurate.
A second useful workflow is to use a new account as a controlled spending lane rather than immediately making it the destination for every bill. For the first few weeks, keep the purpose narrow. You might use it for groceries and transport while leaving major automatic payments where they already work. This gives you a clear test of the app’s fit and reduces the consequences of a setup mistake.
A third insight is that the app can be valuable even if you do not open it constantly. The best routine is not necessarily the most frequent one; it is the one you can maintain. A quick review after income arrives and another after a cluster of purchases may be enough for one person, while someone trying to stop overspending may benefit from checking before making a discretionary purchase.
These workflows also show the trade-off in Chime’s simplicity. A clean mobile experience can make basic actions approachable, but users who want deep categorization, extensive forecasting, or a highly customized financial dashboard may eventually want an additional tool. I would not judge Chime negatively for that boundary. I would simply choose it for the tasks it handles well.
Who should use it and who should look elsewhere
I would recommend Chime to a first-time mobile-banking user who values convenience, wants a straightforward way to monitor everyday money, and is willing to learn the difference between account status and transaction status. It is also a reasonable option for someone who wants to establish a separate routine for spending or saving without beginning with a complicated financial setup.
I would be more cautious about recommending it as the only financial tool for a person with demanding banking needs. If you regularly need in-person help, specialized lending, complex business features, extensive investment services, or a broad international setup, compare it with a traditional bank or a more comprehensive financial platform. A familiar branch network can matter more than a polished phone experience in those circumstances.
It may also be the wrong choice for someone who dislikes managing accounts through a smartphone. The app is built around mobile access, so a user who prefers paper statements, desktop-first banking, or face-to-face assistance should weigh that preference honestly. Convenience only feels convenient when it matches the way you already handle important tasks.
The public age rating is Everyone, which makes the presentation broadly approachable, but that should not be confused with financial suitability for every household. A young person may still need guidance from a parent or guardian when learning about balances, payments, and account responsibilities. The app can simplify access; it cannot replace financial education.
My next-step recommendation after installation
After the first successful action, I would not try to optimize everything immediately. I would use the app through one ordinary pay cycle or spending period, review the activity that actually appears, and note where I still feel uncertain. That reveals more than a long first-night exploration because it tests Chime against real habits rather than imagined ones.
During that trial, pay attention to three questions. Can you find your current balance without hesitation? Can you explain the status of your recent transactions? Can you tell which money is intended for ordinary spending and which is reserved for upcoming obligations? If the answer to all three becomes yes, the app is doing its most important job for you: making your account understandable.
If you decide to keep using it, create a simple personal rule for checking activity and reviewing unusual charges. I would also keep a backup way to contact support and maintain access to the email or phone number connected to the account. These habits are not exciting, but they are exactly what make a finance app dependable over time.
Chime has been developed by Chime and remains free to install, which lowers the barrier to trying it. Its strong 4.7 average and wide adoption make it easy to see why it attracts attention, but my recommendation is based more on its practical shape: it gives beginners a manageable place to start, provided they use it deliberately and read transaction details instead of relying on a single balance number.
My final view is positive but specific. Chime is best when you want mobile banking that feels approachable and focused on everyday control. I would recommend starting with one clear purpose, completing one small verified action, and expanding only after the routine feels comfortable. If your needs are broader than that, pair it with another financial service or choose a more full-service alternative. For a first-time user who wants a reassuring path from installation to a useful banking habit, it is a sensible app to consider.
Pros
- No monthly fees for account maintenance.
- User-friendly interface for easy navigation.
- Instant transaction notifications.
- Access to over 60,000 free ATMs.
- Early paycheck deposit feature.
Cons
- Limited cash deposit options.
- No physical bank branches.
- Mobile check deposit can be slow.
- Not suitable for international use.
- Savings account interest rates are low.
FAQs for Chime® – Fee-Free Banking
What is Chime® and how does it work?
Chime® is a mobile banking app that offers fee-free financial services, including a checking account, savings account, and a Visa debit card. It operates entirely online, allowing users to manage their finances from their smartphones without the need for physical branches. Chime® emphasizes convenience, security, and transparency, making banking accessible and straightforward.
Are there any fees associated with Chime® accounts?
Chime® is known for its fee-free banking model. It doesn't charge monthly maintenance fees, overdraft fees, or foreign transaction fees. However, users should be aware of potential fees from third-party services, such as out-of-network ATM usage. Always review the app’s terms and conditions for the most comprehensive fee information.
How secure is Chime® for managing my finances?
Chime® employs industry-standard security measures to protect your financial information. This includes encryption, account notifications, and two-factor authentication. Additionally, Chime® accounts are FDIC insured up to $250,000 through its partner banks, ensuring your money is safe and secure against unforeseen circumstances.
Can I deposit cash into my Chime® account?
Yes, you can deposit cash into your Chime® account at over 90,000 retail locations such as Walgreens, CVS, and 7-Eleven. This is made possible through Chime’s partnership with the Green Dot network. It's important to note that while Chime® itself doesn’t charge a fee, the retail locations may charge a small service fee for cash deposits.
How does Chime® help with saving money?
Chime® offers several features to help users save money effortlessly. The 'Save When You Spend' feature rounds up transactions to the nearest dollar and transfers the difference to your savings account. Additionally, users can set up automatic transfers to their savings account, encouraging regular savings habits without requiring manual effort.

Chime® – Fee-Free Banking
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@chime.com, visit https://www.chime.com/, or review their https://www.chime.com/privacy.










